Capital Levy and US LLC: What the Asset Protection Myth Really Holds
Few scare topics are promoted as intensively in the German asset protection scene as the «Lastenausgleich» capital levy. At the same time, the idea circulates that a US LLC, thanks to a treaty from the 1950s, could shield against it. What is behind both claims – and which advantages a US LLC actually offers German property owners regardless. Part 3 of our series on US company formation.
- ✛There is no concrete legislative proposal for a new capital levy in 2026.
- ✛The 1952 levy was a tax, not an expropriation – exactly where the treaty argument breaks down.
- ✛Protection via the 1954 friendship treaty is a plausible but untested legal theory.
- ✛What is robust: the LLC's legal and land register capacity, limited liability and flexibility.
- ✛Entity classification determines gift, transfer and income tax – clarify it in advance.
What is a capital levy – and is one coming in 2026?
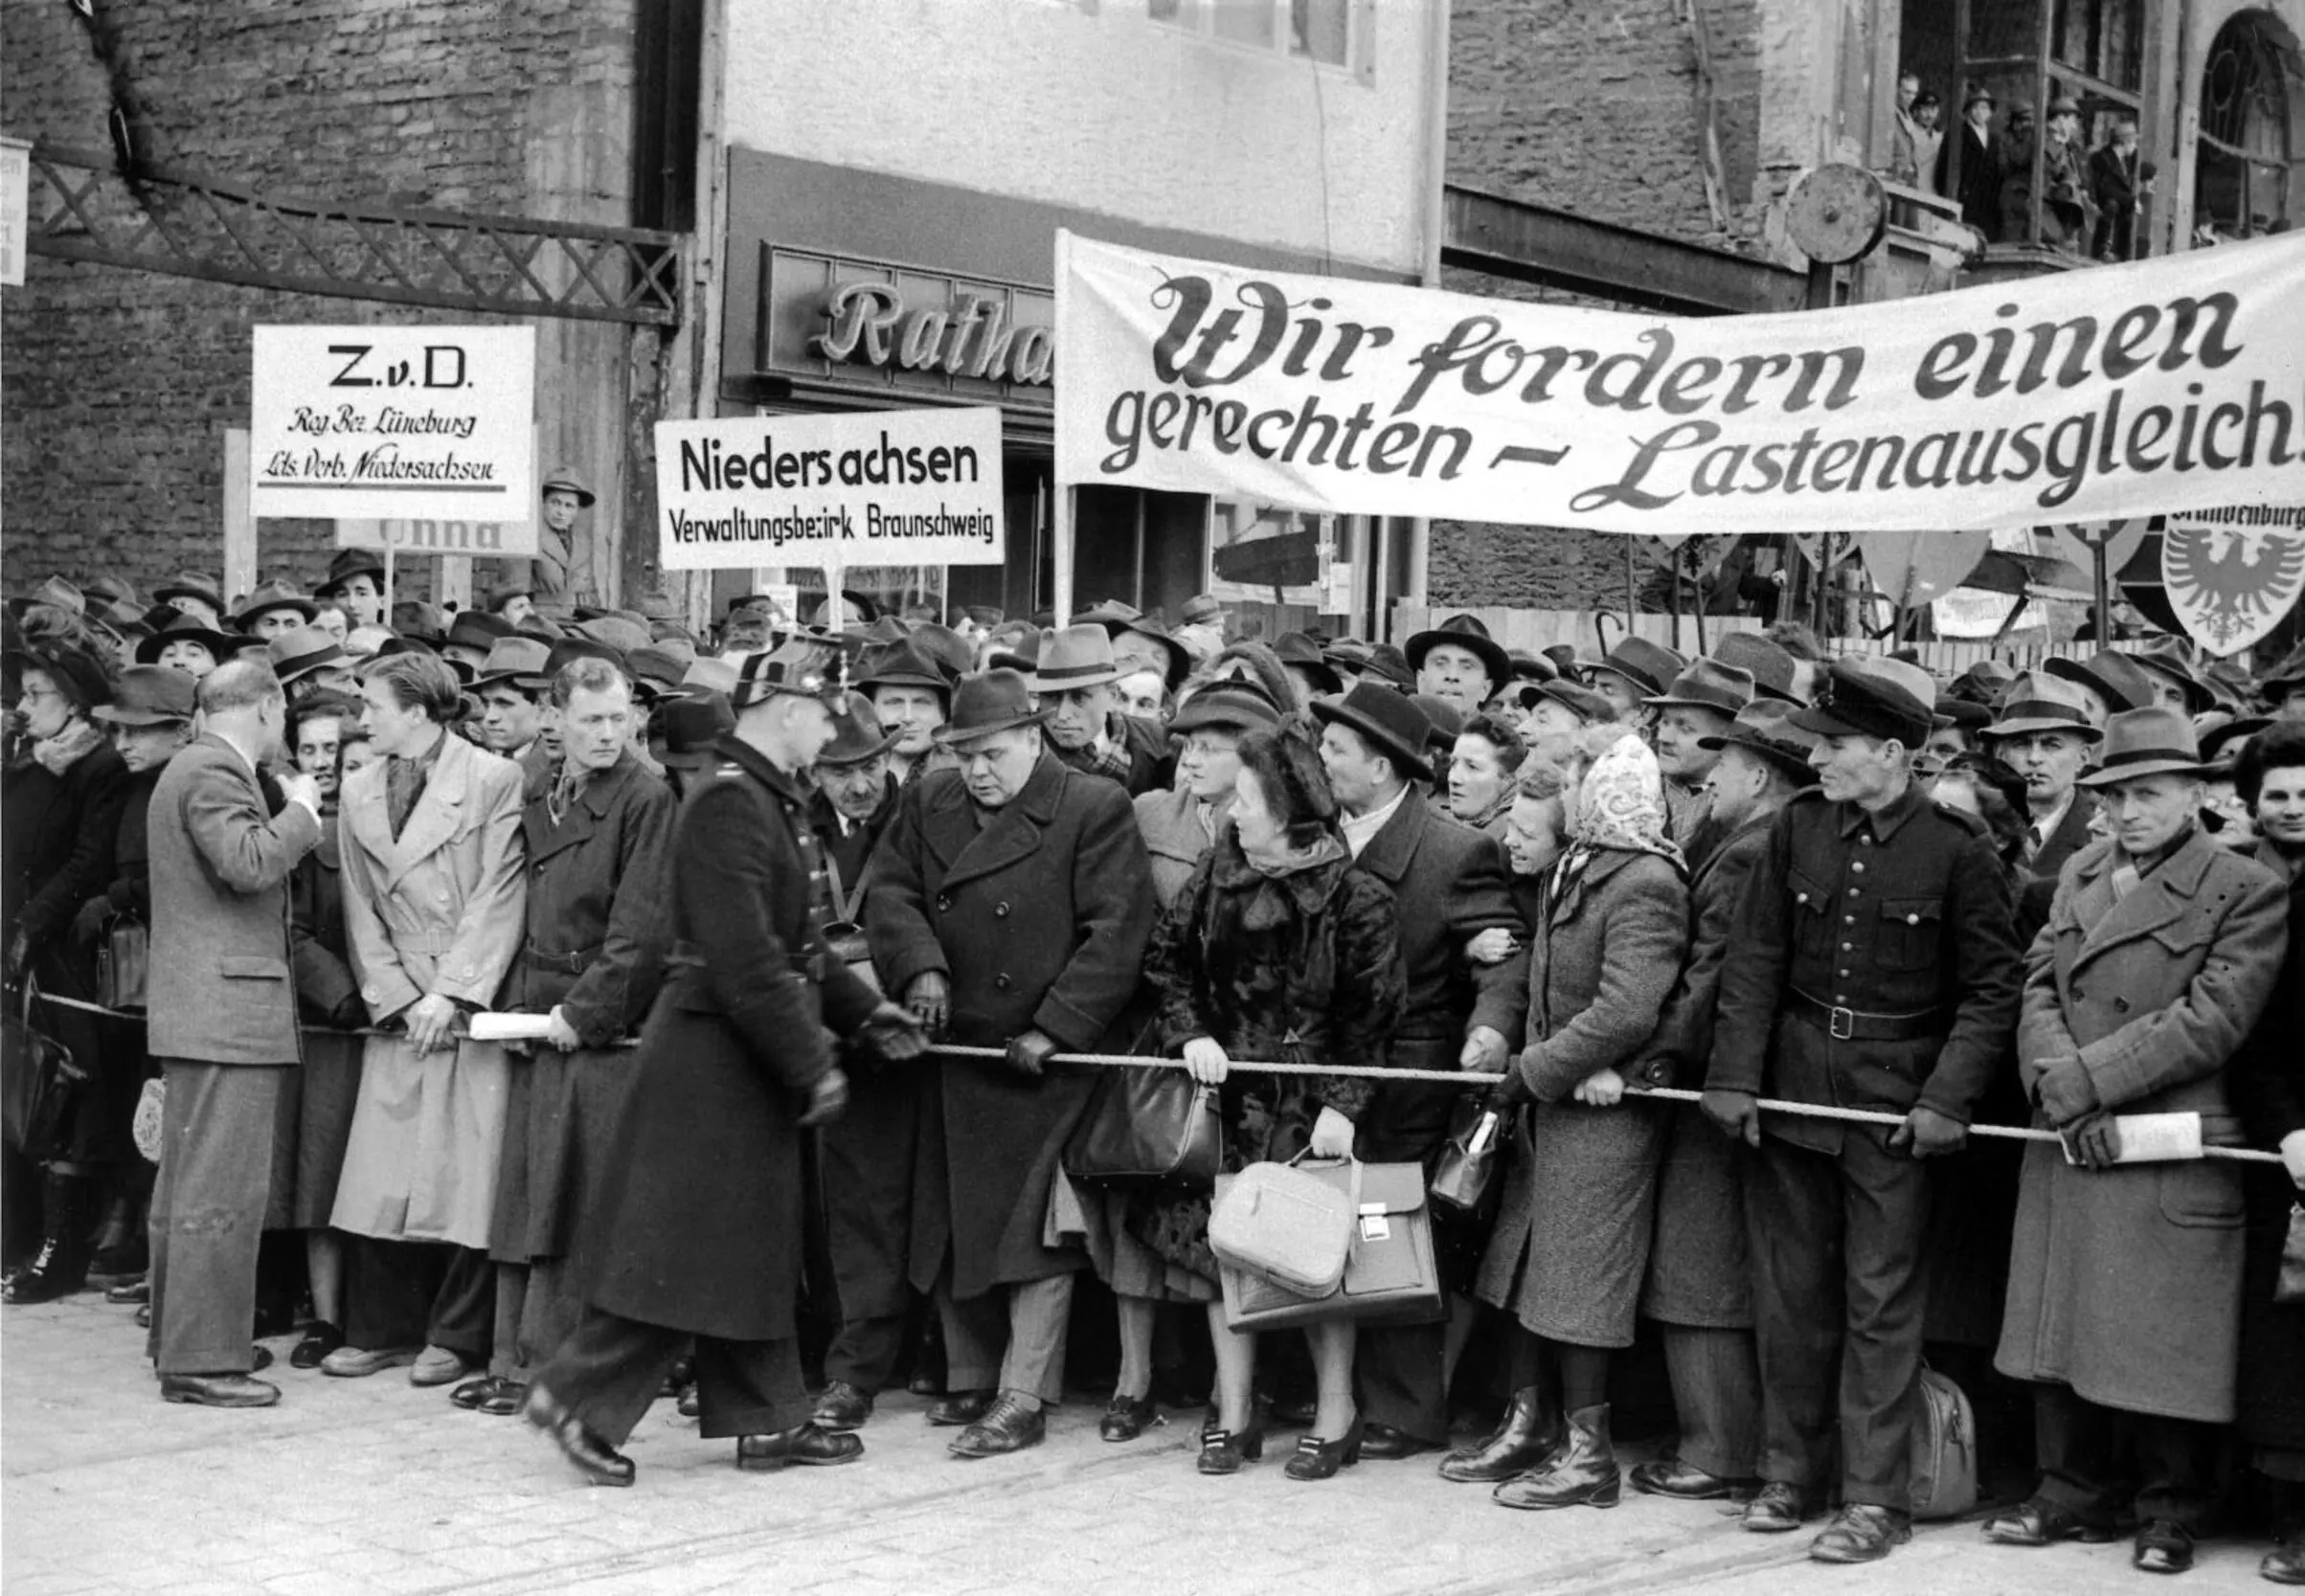
The term comes from Germany's Equalisation of Burdens Act of 1952: a one-off wealth levy of around 50 % of assessed value was imposed to compensate expellees and war victims. It was collected in quarterly instalments over decades and partly secured by a compulsory mortgage in the land register – the annual burden was around 1.67 % of wealth.
Today there is an ongoing political debate, fuelled by high public debt and recurring proposals for a wealth levy. According to consistent reporting, no concrete legislative proposal exists. What does exist is a very active asset protection industry that deliberately creates uncertainty with terms like «year of destiny».
Serious information distinguishes between historical fact, political debate and marketing exaggeration. Anyone building a structure solely on an unspecified scenario is acting on a forecast.
The core idea: US LLC plus friendship treaty
Many providers argue: because the German-American Treaty of Friendship, Commerce and Navigation of 1954 protects US companies against expropriation without adequate compensation, a German property owned by a US LLC could not be «expropriated» under a capital levy.
It is true that the treaty remains in force and Article V protects against uncompensated expropriation. Also true: following the Federal Court of Justice ruling of 29 January 2003 (VIII ZR 155/02), US companies retain legal capacity in Germany even if their administrative seat is in Germany.
Why the construction is weaker than claimed
- ✛The 1952 levy was a tax, not an expropriation. Expropriation clauses apply to sovereign interventions outside tax law, such as nationalisation. A general wealth levy is predominantly considered a tax measure.
- ✛No supreme court confirmation: applying the treaty to a hypothetical levy is an untested legal theory.
- ✛Compensation would be open to interpretation: even if the clause applied, the amount might have to be fought for in court for years.
- ✛No special tax status: a wealth tax would, according to the prevailing view, hit an LLC just like any other form of ownership.
Not legally absurd – but an unproven theory about an unspecified scenario, not a guarantee of protection.
What is genuinely solid about a US LLC in Germany
- ✛Full legal and land register capacity in Germany, based on the friendship treaty and Federal Court case law – even when managed from Germany.
- ✛Limited liability like a corporation, with simple and inexpensive formation and dissolution in the US.
- ✛Flexible succession and ownership rules via the operating agreement.
- ✛Access to US bank and brokerage accounts not always available to German individuals.
These advantages exist regardless of any capital levy scenario – they are the sustainable core of the discussion.

Entity classification: why the LLC usually counts as a corporation
German tax authorities use the Federal Ministry of Finance letter of 19 March 2004 (centralised management, capital structure, transferability of shares, limited liability) to assess whether an LLC resembles a partnership or a corporation. The US election as a disregarded entity plays no role. The Federal Fiscal Court confirms the case-by-case review (e.g. decisions of 18 May 2021, I B 75/20 and I B 76/20; ruling of 20 Aug 2008, I R 34/08) – see also our article on the permanent representative.
In practice, tax offices increasingly classify single-member LLCs as corporations unless clear partnership features exist – such as a «member-managed» structure and an adapted operating agreement.
| As a corporation | As a partnership | |
|---|---|---|
| Contributing the property | Gift tax at the least favourable class, usually plus real estate transfer tax | Generally free of gift tax; for tax purposes the individual remains owner |
| Ongoing rental income | 15 % corporate tax plus solidarity surcharge, trade tax where applicable | Personal income tax rate up to 45 % plus solidarity surcharge |
| Later sale | Subject to corporate tax | Potentially tax-free as for individuals (own use or after 10 years) |
Anyone relying on a specific classification should secure it before contributing property, via a binding ruling from the tax office.
Tax consequences for property in the LLC
A US LLC holding German property does not save German taxes per se – it changes which tax arises and how much:
- ✛Real estate transfer tax: 3.5–6.5 % depending on the federal state for transfers for consideration.
- ✛Gift tax: if the LLC is treated as an «unrelated third party» (tax class III), the lowest allowance of EUR 20,000 and the highest rate apply.
- ✛Speculation period: preserved for a partnership; on a sale to the LLC a new period starts and real liquidity is needed for the purchase price.
- ✛Accounting: usually a simple cash-basis statement for a partnership, corporate profit determination for a corporation.
The LLC-cooperative combination viewed critically
Some recommend passing rental income via a «triple net» lease from the LLC to a German cooperative and minimising tax through provisions and member benefits. This is possible under civil law but delicate for tax purposes:
- ✛Arm's length principle: a lease «far below market value» between related parties is scrutinised particularly closely – it suggests hidden profit shifting.
- ✛Member benefits are not a free pass: cooperatives are also subject to the rules on hidden profit distributions and benefits in kind.
- ✛Complexity increases audit risk: LLC plus cooperative plus related-party lease stands out.
Such models may make sense in individual cases but require arm's-length contracts, clean documentation and review by an independent German tax adviser. «Tax burden close to zero» is a goal of aggressive planning, not a reliable result.
Conclusion and how SWICOR supports you
- ✛A capital levy is not law in 2026, but a recurring topic of debate.
- ✛Protection via the friendship treaty is a plausible but untested theory – the historical levy was a tax.
- ✛The solid advantages of the LLC are legal and land register capacity, limited liability and flexibility.
- ✛Entity classification determines the tax consequences – with a tendency towards corporation.
- ✛Cooperative combinations only with individual professional advice.
SWICOR helps you assess a US LLC structure realistically – without fear marketing, but without hiding the genuine advantages either. Choosing the legal form is covered in part 1 of the series on US corporation, LLC and LP; on transparency, see also the EU asset register.
Check whether a US LLC makes sense for your property.
Company formation USA →Frequently asked questions
Is a capital levy really coming?
There is currently no concrete legislative proposal. The topic is debated politically and in the media but in 2026 is neither adopted nor in the legislative process.
Does a US LLC reliably protect against a future capital levy?
No. The friendship treaty protects against uncompensated expropriation – whether a future wealth levy would count as expropriation is unresolved and historically rather unlikely, since the previous levy was a tax.
Is a US LLC treated as a partnership or corporation in Germany?
Entity classification decides case by case. A member-managed LLC with a suitable operating agreement can count as a partnership; otherwise tax offices increasingly classify it as a corporation.
Can I contribute property to an LLC tax-free?
Only if it is recognised as a partnership. As a corporation, the contribution usually triggers gift tax at the least favourable class and real estate transfer tax.
Is combining an LLC with a cooperative worthwhile?
Possible in individual cases, but considerably riskier than often presented. Related-party contracts must be at arm's length; a tax burden «close to zero» is not a guaranteed result.
Asset protection with a realistic assessment
We check whether a US LLC fits your property and asset situation – and set it up properly, coordinated with your tax adviser.
This article is a general analysis and does not replace individual tax or legal advice. Regulations change; the information reflects the status at the date of publication.